Lucid Q1 Financials and Forward Looking

Well, he is known to be a big on financial discipline.

Details on Topspeed initiative at Schindler introduced by Napoli. This is exactly what Lucid needs!

Key Strategic Goals
  • Digital Connectivity: Linking more than 30% of the maintenance portfolio to the cloud, resulting in a 50% increase in digital revenue.
  • Operational Efficiency: Reducing the "loss rate" by 50% through improved preventive care and better supply chain management.
  • Innovation: Launching a new standardized modular elevator platform to reduce complexity across the entire value chain.
  • Sustainability: Drastically reducing CO2 emissions, with some digital service contracts achieving up to a 99.5% reduction in total emissions. [1, 2, 3, 4, 5]


📈 Financial Impact & Results [1]
The initiative required a total investment of CHF 167 million over four years, which Napoli expected to pay back within the same timeframe. The results were significant: [1]
  • Margin Recovery: The operating profit (EBIT) margin returned to double digits (10.3%) by 2023.
  • Profit Growth: Net profit surged by 42% to CHF 935 million in 2023 following the program's completion.
  • Performance: Adjusted EBIT margin further climbed to 11.4% in the first half of 2024, despite difficult global market conditions. [1, 2, 3]

I was already impressed by seeing Napoli's LinkedIn. But seeing these initiatives that he lead, now DAMN that is something else. I agree, I think he could be just the kind of CEO that Lucid needs
 
Actually, it’s very different. Stock investing is only gambling if you don’t understand the company. Yes, extraneous factors can affect the company in the future, but no one knows what they are. But at the time you buy, if you do due diligence, and feel comfortable with risk, you buy the stock.

With Polymarket it’s a coin toss…..very different.

But when buying a stock on meme craze, now that’s gambling.
Thank you for explaining how stock investing works. I had no idea.
 
Lucid has some good designs and technologies. Lucid's big problem is their (lack of) discipline in product development, supplier co-development, supply chain management, SW integrity, and lately, Service.

Lucid should be reminded of the warning label on convex car rear-view mirrors (embellishing) "the objects (vis-a-vis competitors) in your rear-view mirror are actually closer than you might think!"

I don't see Lucid's problems as unique or technically or business-wise hard to solve. They need a cultural transformation, emphasizing ownership and disciplined solutions vs highlighting and rewarding "Gee-Whiz " stuff. If Lucid doesn't make the cultural change, it will go the way of many of the British car companies like Jaguar. Perhaps Lucid does not aspire to be like Toyota. But "Jaguar-like" culture is a sure path to extinction.
Yes they are sort of a Pre-teen right now, getting excited about lots of shiny things and forgetting the boring stable stuff or consistent process to grow up into. I trust them to get there, different CEOs for different stages of the company....
 
Yes they are sort of a Pre-teen right now, getting excited about lots of shiny things and forgetting the boring stable stuff or consistent process to grow up into. I trust them to get there, different CEOs for different stages of the company....
It is a good thing that some of us eventually got past adolescence! 😝
 
What I read was that about 2000 cars cannot be sold due to issues with the second row seats from the supplier
I had mobile service out today to do why seasonal wheel/tire swap
The take from the tech is the guy designing some elements of the seating for the Gravity is choosing designs/specifications that are hard to achieve by the supplier
Apparently the service center has had some tough experiences dealing with these second row seats for Gravity models that were sold
 
Recent stock pricing leads me to speculate that some decent April sales figures are lurking about.
 
Recent stock pricing leads me to speculate that some decent April sales figures are lurking about.
...the nearly 52 week low? After a 10:1 reverse stock split?!?!

No. The fact that the stock has moved north of $6.00/share after all of last quarter's missteps, dilution, production, inventory, financials and a recent investor briefing that was IMO questionable. Some decent Gravity figures would help the viability debate a lot, and I am expecting them to arrive this quarter, including April.
 
Recent stock pricing leads me to speculate that some decent April sales figures are lurking about.
Yeah, I noticed they said March had a rebound on sales and deliveries, and I wonder how much that momentum will carry into April and onwards
 
Right I will hold patience until Q2 closes, but if they have a full quarter of production and deliveries I fully expect Gravity to be in 2nd place after R1S. It was already 4th in Q1 with a stop sale, and Model X will be gone (it was 2nd), and I think it overtakes Escalade easily. Plus by the end of the year it will be nipping on the R1S heels, I don't think people are taking into account how much the R2 will take from R1. I don't know why you would get a new R1S over an R2 or a lightly used off-lease R1S or a new Gravity....
 
Recent stock pricing leads me to speculate that some decent April sales figures are lurking about.
Motor intelligence reported April sales of 290 cars and 550 truck sales (840 total) for Lucid in the US. Lucid consistently pushes back on these figures as incorrect. Based on last quarter numbers I’d estimate the real figure is between 1200-1500.
 
No. The fact that the stock has moved north of $6.00/share after all of last quarter's missteps, dilution, production, inventory, financials and a recent investor briefing that was IMO questionable. Some decent Gravity figures would help the viability debate a lot, and I am expecting them to arrive this quarter, including April.
The US Mint discontinued the penny, so the market is now rounding up
 
Right I will hold patience until Q2 closes, but if they have a full quarter of production and deliveries I fully expect Gravity to be in 2nd place after R1S. It was already 4th in Q1 with a stop sale, and Model X will be gone (it was 2nd), and I think it overtakes Escalade easily. Plus by the end of the year it will be nipping on the R1S heels, I don't think people are taking into account how much the R2 will take from R1. I don't know why you would get a new R1S over an R2 or a lightly used off-lease R1S or a new Gravity....
Personally I think Q2 is a good recovery time for Gravity sales, then Q3 in general as a way to gauge the initial progress of Silvio's direction. Q4 2026 and Q1 2027 I think will be the big milestones for Silvio's initiatives.
 
Personally I think Q2 is a good recovery time for Gravity sales, then Q3 in general as a way to gauge the initial progress of Silvio's direction. Q4 2026 and Q1 2027 I think will be the big milestones for Silvio's initiatives.
To me, the big test of Silvio's acumen will be how quickly he starts ramping the service centers... Not so much to solve the current service backlog, although that's hugely important, but more importantly to begin demonstrating that Lucid intends to be well-equipped to service mid-size volumes.
 
To me, the big test of Silvio's acumen will be how quickly he starts ramping the service centers... Not so much to solve the current service backlog, although that's hugely important, but more importantly to begin demonstrating that Lucid intends to be well-equipped to service mid-size volumes.
Yeah, I meant in that the effects from Q2 2026 onwards to include service centers, not just Air/Gravity manufacturing and midsize launch. Even if Silvio goes flat out on expanding service center locations starting right now, it'll take months to get staffing, tooling, logistics, and the facilities set up.
 
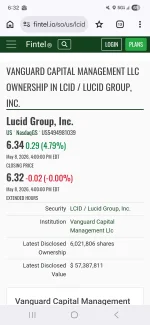
Various Vaguard portfolios registered their 13F's today 5/8. They bought 12 million shares over 6 portfolios in the first quarter. I've attached one of them that bought 6 million
 

Attachments

  • Screenshot_20260508_183214_Chrome.webp
    Screenshot_20260508_183214_Chrome.webp
    92.5 KB · Views: 73
Various Vaguard portfolios registered their 13F's today 5/8. They bought 12 million shares over 6 portfolios in the first quarter. I've attached one of them that bought 6 million
While I did add more LCID to my Vanguard portfolio, I can confirm that the 6 million one was not mine.
 
Yeah, I meant in that the effects from Q2 2026 onwards to include service centers, not just Air/Gravity manufacturing and midsize launch. Even if Silvio goes flat out on expanding service center locations starting right now, it'll take months to get staffing, tooling, logistics, and the facilities set up.
They recently showed the Gravity service vehicles, maybe they are banking on not needing that many full service centers.
 
My guess is a big reason why service is overwhelmed is because (a) all of the software issues on Gravity and (b) random hardware issues that Lucid is continuing to refine on the production line with time. If they expect these issues to subside in the next few months, it would explain why they don't want to rush to expand service now, especially in the context of them generally being in cost-cutting mode.

That being said, it's a good thing I'm not having issues with my Air because my pitch fork would be out if I was and they told me I'd have to wait 2 months!
 
Back
Top