LUCID Gravity Lease vs Finance

Do you mind posting the following:

1- vehicle config summary $ cost ) no taxes and fees)
2- amount due before delivery
3- monthly $ payments
4- financed amount ( includes taxes&fees)
5- residual value
You already provided
5- term in months
6- allowed miles/year

This way can extrapolate to other cars. Not sure how they price if they give approval with November ‘estimate’ and deliver in December.

Thanks.
 
Do you mind posting the following:

1- vehicle config summary $ cost ) no taxes and fees)
2- amount due before delivery
3- monthly $ payments
4- financed amount ( includes taxes&fees)
5- residual value
You already provided
5- term in months
6- allowed miles/year

This way can extrapolate to other cars. Not sure how they price if they give approval with November ‘estimate’ and deliver in December.

Thanks.

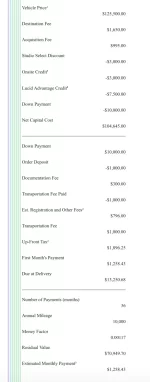
Sure! I'm in Northern California (to the extent that matters for leasing rates), and my order is attached to the Rocklin studio. The SA's email said:

A few things to note: the estimated money factor is 0.00117, and the estimated residual is $64,601.25. This is for a 36-month lease w/ 15K miles per year. The actual money factor may vary slightly depending on the credit application.

And the lease quote pdf itself contained this:


Lucid 25-12-05 lease estimate.webp
 
Sure! I'm in Northern California (to the extent that matters for leasing rates), and my order is attached to the Rocklin studio. The SA's email said:


And the lease quote pdf itself contained this:


View attachment 34913
I've never leased and find the whole thing confusing to compare to an outright (no loan) purchase. But lemme take a quick stab at this. 36 payments of $1703.39 = $61,308. If the residual is $64,401 (or maybe that's a different car?), that's a total of $125,709 if you want to buy the car outright then? And I presume there's sales tax on that $64k at that point, for another $4k or so.

Sounds like pretty much the same as the cash purchase, right?
 
I've never leased and find the whole thing confusing to compare to an outright (no loan) purchase. But lemme take a quick stab at this. 36 payments of $1703.39 = $61,308. If the residual is $64,401 (or maybe that's a different car?), that's a total of $125,709 if you want to buy the car outright then? And I presume there's sales tax on that $64k at that point, for another $4k or so.

Sounds like pretty much the same as the cash purchase, right?
I may not be the best person to respond, as I've also never leased before. Normally I buy my vehicles outright. I'm leasing only to protect myself from Lucid failing (which seems somewhat more likely as Gravity demonstrates how bad their software engineering is) and to provide an easy out in 3 years if my Gravity ultimately turns out to be buggy enough that I regret buying it. The $7500 incentive compensating me for some of the financing cost helps make the lease more appealing.

In California, you pay sales tax on each lease payment, 7.25% in my specific county. That is baked into the $1703.39 in my quote, so there's no sales tax charged beyond what is quoted. An online lease calculator breaks the monthly cost out like this:

Monthly Depreciation: $1,378.99
Monthly Interest: $209.25
Monthly Tax: $115.15


You can probably argue about what the right mindset is for comparing the leasing tax costs to the cash purchase tax costs. If the vehicle works out well, I may well purchase the vehicle at lease end, paying sales tax on the residual value, and effectively having a wash on tax cost. Leasing still has a tax advantage, as I don't pay tax on the $7500 discount ($6505 net after lease acquisition fee), and the time value of money for paying the sales tax on the residual value in 3 years instead of today.

All that said, my own personal calculation is that if I buy the vehicle outright, I'm spending $56,148.75 for the initial 3 years (vehicle cost + destination fee - residual), and if I lease I'm spending $57,176.64 for the initial 3 years (36 payments, less the $115.15 monthly sales tax). So leasing is $1027.89 more. Obviously a full time-value-of-money calculation will change that somewhat, as will comparing a financed sale instead of a cash purchase.

All in all, I feel like the protection I get from leasing gives me a hard-to-value insurance policy that is worth it.
 
I may not be the best person to respond, as I've also never leased before. Normally I buy my vehicles outright. I'm leasing only to protect myself from Lucid failing (which seems somewhat more likely as Gravity demonstrates how bad their software engineering is) and to provide an easy out in 3 years if my Gravity ultimately turns out to be buggy enough that I regret buying it. The $7500 incentive compensating me for some of the financing cost helps make the lease more appealing.

In California, you pay sales tax on each lease payment, 7.25% in my specific county. That is baked into the $1703.39 in my quote, so there's no sales tax charged beyond what is quoted. An online lease calculator breaks the monthly cost out like this:

Monthly Depreciation: $1,378.99
Monthly Interest: $209.25
Monthly Tax: $115.15


You can probably argue about what the right mindset is for comparing the leasing tax costs to the cash purchase tax costs. If the vehicle works out well, I may well purchase the vehicle at lease end, paying sales tax on the residual value, and effectively having a wash on tax cost. Leasing still has a tax advantage, as I don't pay tax on the $7500 discount ($6505 net after lease acquisition fee), and the time value of money for paying the sales tax on the residual value in 3 years instead of today.

All that said, my own personal calculation is that if I buy the vehicle outright, I'm spending $56,148.75 for the initial 3 years (vehicle cost + destination fee - residual), and if I lease I'm spending $57,176.64 for the initial 3 years (36 payments, less the $115.15 monthly sales tax). So leasing is $1027.89 more. Obviously a full time-value-of-money calculation will change that somewhat, as will comparing a financed sale instead of a cash purchase.

All in all, I feel like the protection I get from leasing gives me a hard-to-value insurance policy that is worth it.
The $4k tax I referenced was for buying the vehicle post-lease, not the tax added to the lease payment. But yeah, overall that jives with my read too. All in all the $7500 benefit (minus the acquisition fee) seems to be eaten up by leasing costs, and ends up being roughly a wash (time value of our money outlay notwithstanding). Doesn't look like we really save any money leasing vs paying cash.

The real value is as insurance against Lucid going belly up, or against the Gravity being a flop and the value dropping a ton. Not sure I wanna mess with the extra trouble for that, even though it might be the smart play. I have a trade-in too (if I can get a good enough KBB offer for it), which could complicate things as well.
 
Has anyone been able to get a lease with MF of 0.00177 that @TahoeMichael got?
Local Lucid Studio quoted 0.00234 today, which is essentially unchanged from a month ago.
Wondering if BoA raised the number?
 
Has anyone been able to get a lease with MF of 0.00177 that @TahoeMichael got?
Local Lucid Studio quoted 0.00234 today, which is essentially unchanged from a month ago.
Wondering if BoA raised the number?

Are you talking about a 36-month lease? I remember reading that that was the only one whose cost seemed to drop meaningfully between November and December.

In my case, the monthly payment on the 36-month lease that I signed in December was roughly 10% lower than on the 36-month lease "offer" that I received in November---taxes included on both. (I know the residual values for both, but I don't know how to calculate the money factor.)
 
Are you talking about a 36-month lease? I remember reading that that was the only one whose cost seemed to drop meaningfully between November and December.

In my case, the monthly payment on the 36-month lease that I signed in December was roughly 10% lower than on the 36-month lease "offer" that I received in November---taxes included on both. (I know the residual values for both, but I don't know how to calculate the money factor.)
Yes, 36 month lease.
The numbers shown to me were lower, but not 10% difference.
 
Has anyone been able to get a lease with MF of 0.00177 that @TahoeMichael got?
Local Lucid Studio quoted 0.00234 today, which is essentially unchanged from a month ago.
Wondering if BoA raised the number?
My MF is 0.00177.
I received a hefty $13,500 (3,000 + 3,000 + 7,500) in total credits.
 

Attachments

  • Gravity_Lease.webp
    Gravity_Lease.webp
    46.5 KB · Views: 247
And for luxury car leases, you can always negotiate down your buyout offer.
I did it for my X5 in 2024. BMW never really wanted it back; too much hustle getting it prepped for CPO sale.
Of course, the X5 was worth less than their estimated residual. My buyout discount was about $6,300.

It'll likely be the same for the Gravity. And I'll gladly do a buyout for several thousands off residual.
 
And for luxury car leases, you can always negotiate down your buyout offer.
I did it for my X5 in 2024. BMW never really wanted it back; too much hustle getting it prepped for CPO sale.
Of course, the X5 was worth less than their estimated residual. My buyout discount was about $6,300.

It'll likely be the same for the Gravity. And I'll gladly do a buyout for several thousands off residual.
I assume you did that as the lease wrapped up? Or are you talking about an upfront negotiation?
 
I wonder if they're giving different rates in different states? My lower money factor was for a California lease quote.
Was thinking the same, too.
Well, since everything else in Calif is so much more expensive, you guys need to have a break somewhere.
 
Has anyone been able to get a lease with MF of 0.00177 that @TahoeMichael got?

Re-checking my correspondence with the SA, on November 22, I was offered a money factor of .002 on a 36-month lease (and .00238 for 48 months). Here's a screenshot.

Screenshot.webp


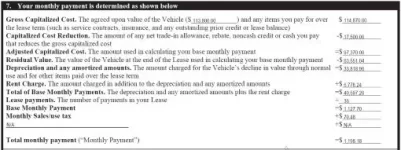
For the lease I signed last week (based on a revised December "offer"), I don't know the money factor. Google tells me that the formula for calculating the money factor is: Rent Charge / ((Capitalized Cost + Residual Value) x Lease Term). But I'm not sure which of the three Capitalized Cost figures from the lease agreement to use in that calculation. Further complicating things, the $113,800 "Agreed upon value of the Vehicle" figure incorporates a $1650 "Destination Fee" and a $2000 "Loyalty Credit"---the price of the vehicle as configured was $114,150---that aren't actually mentioned in the lease agreement itself. (Based on this post, I assume that I will have to pay income tax on the "Loyalty Credit.")

In any event, here are the relevant details from the lease agreement, just in case they are useful to anyone else. FWIW, I am in Massachusetts.

Screenshot 2025-12-16 212454.webp

Screenshot 2025-12-16 212539.webp
 

Attachments

  • Screenshot 2025-12-16 175028.webp
    Screenshot 2025-12-16 175028.webp
    22.2 KB · Views: 182
Re-checking my correspondence with the SA, on November 22, I was offered a money factor of .002 on a 36-month lease (and .00238 for 48 months). Here's a screenshot.

View attachment 35200

For the lease I signed last week (based on a revised December "offer"), I don't know the money factor. Google tells me that the formula for calculating the money factor is: Rent Charge / ((Capitalized Cost + Residual Value) x Lease Term). But I'm not sure which of the three Capitalized Cost figures from the lease agreement to use in that calculation. Further complicating things, the $113,800 "Agreed upon value of the Vehicle" figure incorporates a $1650 "Destination Fee" and a $2000 "Loyalty Credit"---the price of the vehicle as configured was $114,150---that aren't actually mentioned in the lease agreement itself. (Based on this post, I assume that I will have to pay income tax on the "Loyalty Credit.")

In any event, here are the relevant details from the lease agreement, just in case they are useful to anyone else. FWIW, I am in Massachusetts.

View attachment 35204
View attachment 35205
Thanks so much for the details. Really appreciate your thoughtfulness.
My SA couldn't lower the MF, so I likely will go the 1.99% loan, which isn't too bad.
My car has been at SC for the last week with no movement on the software update.
As of Saturday, there were 5 Gravities ahead of me, so probably another week in waiting.
 
For my DE the residual after 36 months was almost exactly 50%. Different states handle the sales tax differently, so you need to factor that in. For example, in Georgia you only pay the sales tax on the value of the lease (depreciation), then if you buy the car at the end of the lease you pay the remaining sales tax on the residual value of the car. Whereas in Texas I believe you pay the sales tax on the entire value of the car if you lease. I calculated that, at least for me, leasing with the tax credit was approximately 5% more expensive than buying (considering the time value of money). I felt the optionality of returning the car at the end of the lease if Lucid went belly up or if the car was a lemon was worth the extra 5%. I will probably buy the car at the end of the lease, unless something disastrous happens.
 
Back
Top