- Joined
- Apr 26, 2026
- Messages
- 407
- Reaction score
- 200
- Cars
- Audi e-tron Sportback 55
Haha OK yeah that can be the reasonWe have the world's worst drivers too which doesn't help.

Haha OK yeah that can be the reasonWe have the world's worst drivers too which doesn't help.
Honestly, $2,112 a year doesn’t sound completely crazy for a Lucid Air in Tempe, especially with $500K liability and UM/UIM limits, but I’d still shop it around. The increase from $1,692 to $2,112 is significant, particularly with your clean driving records and lower mileage. I’d get several quotes using the exact same coverage and deductibles before deciding. I’d also ask Acuity to clearly explain how they determine the total-loss value and why they are rating the car at MSRP rather than what you actually paid. Your agent may have found the best option already, but I’d want to see the competing quotes myself before accepting a 25% premium increase.Curious to see if my situation is typical. I'm sharing a lot of detail (maybe too much?), but history and coverage differences can have a huge impact.
2023 Lucid Air Pure AWD - MSRP of $96.6k, but paid $75.2k + tax & fees. (Was told that my insurer (Acuity) insisted on insuring at MSRP instead of the price paid, whatever that means. My guess is the 'if totaled' value would be about half the MSRP. )
Two drivers, and insuring two cars. I'm 75 and wife is 76. Both of us have flawless driving records with no 'at fault' accidents in our lives. (I got rear ended about 9 years ago.) Solid financial scores. Car is based in our Tempe, AZ residence. (My rates had a significant uptick when we moved from North Scottsdale to Tempe, despite a huge reduction to our annual mileage. I was told due to population density, proximity to the university, and local accident/theft rates, although the car is parked in a very secure location.)
Lucid's annual premium due this week is $2,112. It was $1,692 when the car was first insured in 12/23. I also came across https://united-healthcare.pissedconsumer.com/customer-service.html while looking into customer service resources, and our other Tempe car, a 2002 Lexus SC430, is $847/year with the same coverage. We've been with the carrier since 2020, so some loyalty discounts are in place.
Here's the coverage...
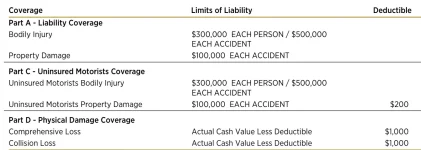
Liability - $500k per person/$500k per occurrence
Uninsured motorists - $500k each person/$500k each accident
Underinsured motorists -$500k each person/$500k each accident (In each of the above, the $500k is required by my personal liability umbrella.)
Comprehensive deductible - $250 (No specific glass coverage. To be handled here.)
Collision deductible - $2,500
Agent looked at alternative carriers, and we explored coverage changes, but this came out as optimal. Reasonable? Doesn't seem so to me.

Well let’s also consider that we continue to let drunk drivers keep driving. We let drivers slide when they share a cross walk with pedestrians. We let a lot of poor drivers continue to drive with no real training.We have the world's worst drivers too which doesn't help.


That USAA quote sounds very good. What are the limits on your coverages, what are your deductibles and what state are you in?Using the VIN from my order for the 2026 AGT w/ glass canopy, USAA quoted me $1500/year. I switched my order to a 2027 w/ DDP, and I suspect my quote will change once I provide the new VIN.
I’m in Tennessee. I’ve also been driving for 50 years. I don’t know if (older) age impacts rates.That USAA quote sounds very good. What are the limits on your coverages, what are your deductibles and what state are you in?
THx.
Thx for the info. I had USAA on my '23 Touring with $250/$500k coverage (it seems most folks on this forum carry the $250/$500k limits because they're needed to get an umbrella policy.). I had 1 at fault accident & 1 moving violation in my last 3 years and my USAA quote was astronomical. It was twice what my quote from State Farm was (which wasn't low, but was low only by comparison with USAA). I had had USAA for decades because of their superior service but have found their service has deteriorated a bit while their pricing has exploded. That's a bad confluence of moves by an insurer.I’m in Tennessee. I’ve also been driving for 50 years. I don’t know if (older) age impacts rates.

In California this is liable to get you into a situation where your house is uninsurable as in many ares insurance companies are refusing to write new policiesLoyal customers are punished with increasing rates.
Change your insurance company every couple years to keep lower rates.

PURE actually combats this; for your first five years, a small separate fee is added to your premiums as a surplus contribution. These funds provide extra financial backing to strengthen their claims-paying ability without relying on outside capital. At your fifth renewal you no longer pay these surplus contributions, reducing the overall cost.Loyal customers are punished with increasing rates.
Change your insurance company every couple years to keep lower rates.
How did you manage to get Nationwide? I was a Nationwide Private Client customer for over a decade (home + auto + umbrella) until they decided to leave California and sent me a letter stating that they would no longer insure or renew California customers a few years ago.I'm 68, perfect driving record and drive around 24k/year
2025 Lucid Air Pure — California - Nationwide is on my side!
Total: $240.18 per month ($2,882.16 annually)
- Comprehensive: $250 deductible, including full safety-glass coverage — $56.71/month
- Collision: $500 deductible — $99.31/month
- Collision-deductible waiver — $0.50/month
- Rental reimbursement: $40/day, up to $1,200 per accident — $4.83/month
- Bodily-injury liability: $250,000/$500,000 — $34.26/month
- Property-damage liability: $100,000 — $22.09/month
- Medical payments: $5,000 per person — $2.36/month
- Uninsured-motorist bodily injury: $250,000/$500,000 — $20.12/month
I too had Nationwide Private client for more than a decade (home + auto + umbrella) . In CA (Los Angeles), two years ago, I got a similar letter that they would not renew (never had a claim). At a substantial premium increase for all my insurances. I went with CHUBB Masterpiece. Unfortunately I had a claim for a totaled BMW iX car, not at fault, which put me in the Gravity I now have. The way CHUBB handled the claim will keep me with them even if I could find less expensive insurance. They are indeed a class act. PureAirTouring's quote seems like a bargain. A lot depends on garaged ZIP code.How did you manage to get Nationwide? I was a Nationwide Private Client customer for over a decade (home + auto + umbrella) until they decided to leave California and sent me a letter stating that they would no longer insure or renew California customers a few years ago.

They have different companies inside of theirs, they might have came back in a few select markets. They pulled out of Idaho and are coming back in here as well but very picky about it. Eventually all the carriers all end up only wanting to insure the same things which leads to something that looks less like competition and more like a cell phone plan where they are all kinda the same.How did you manage to get Nationwide? I was a Nationwide Private Client customer for over a decade (home + auto + umbrella) until they decided to leave California and sent me a letter stating that they would no longer insure or renew California customers a few years ago.