You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
What's the take away from the Lucid earnings call? I didn't attend. What was your take?
- Thread starter BS8899
- Start date

- Joined
- Jul 1, 2025
- Messages
- 283
- Reaction score
- 434
I will say positive to be modest.
Napoli is delivering.
Q4 will gives more insight, but I think the short term goals and cosmos info they plan to release in Q1 2027 will give us a better idea of where we are going.
Honestly; I think Napoli is proving he is the right man for the job.

- Joined
- Jun 22, 2024
- Messages
- 1,595
- Reaction score
- 1,326
- Location
- Naperville, IL
- Cars
- 14 CR-V EXL, 26GravityGT
- Referral Code
- W772ZCOT
Same, I heard some meaningful progress, acting like a real company trying to be responsible and responsive. I heard him slip saying Cosmos and Earth but might have been reading too much into it. They have additional credit from PIF, but I think it's basically money to keep them treading water and no more extra for investment. Once Mid-size and AMP-2 are done a huge amount of cash flow drain will decrease, I think they said those two programs were something like 40% of the 1.4B spend.
- Joined
- May 19, 2025
- Messages
- 536
- Reaction score
- 699
- Cars
- BMW X1
Personally I wouldn't be surprised if Earth comes relatively close after Cosmos, especially since they're targeting 95% parts shareSame, I heard some meaningful progress, acting like a real company trying to be responsible and responsive. I heard him slip saying Cosmos and Earth but might have been reading too much into it. They have additional credit from PIF, but I think it's basically money to keep them treading water and no more extra for investment. Once Mid-size and AMP-2 are done a huge amount of cash flow drain will decrease, I think they said those two programs were something like 40% of the 1.4B spend.
- Joined
- May 19, 2025
- Messages
- 536
- Reaction score
- 699
- Cars
- BMW X1
Steady and measured. Overall I remain cautiously optimistic with Silvio.
- 60% reduction in safety incidents in AMP1
- on track for $1.4 billion cash flow improvement for 2026
- Robotaxi w/ Nuro and Uber remains on target
- Cosmos scheduled for official reveal Q1 2027, with ramp up of production on H2 2027. European expansion remains in line with targeted midsize launch.
- AMP2 remains on track, including tooling such as stamping, paint, body, etc. Infrastructure for the factory is also progressing well
- Liquidity into Q4 2027
- 70% reduction in warranty claims, with 16% reduction in warranty costs and 20% improvements in wait times.
- 60% reduction in safety incidents in AMP1
- on track for $1.4 billion cash flow improvement for 2026
- Robotaxi w/ Nuro and Uber remains on target
- Cosmos scheduled for official reveal Q1 2027, with ramp up of production on H2 2027. European expansion remains in line with targeted midsize launch.
- AMP2 remains on track, including tooling such as stamping, paint, body, etc. Infrastructure for the factory is also progressing well
- Liquidity into Q4 2027
- 70% reduction in warranty claims, with 16% reduction in warranty costs and 20% improvements in wait times.
Last edited:
- Joined
- May 19, 2025
- Messages
- 536
- Reaction score
- 699
- Cars
- BMW X1
20% improvement in terms of service wait times. Can't recall if there was a discussion on expanding the service centres during the call but I've seen some LinkedIn posts by Lucid employees that talk about new service centres being opened upNothing about service backlogs/expansion?
- Joined
- Jan 3, 2022
- Messages
- 7,602
- Reaction score
- 8,735
- Location
- San Francisco Bay Area
- Cars
- Gravity GT, XC40 P8 EV
- Referral Code
- 3OKY7YGA
"Our significant investment in service has already cut wait times by around 20%, supported by a 40% increase in service technicians, 15% more mobile service capacity, and an expanded service footprint."20% improvement in terms of service wait times. Can't recall if there was a discussion on expanding the service centres during the call but I've seen some LinkedIn posts by Lucid employees that talk about new service centres being opened up
Like I’ve always been saying…..they will never go bankrupt…..PIF will support until they establish. Napoli is looking to be the perfect choice for CEO.
I’m optimistic Q4 will show even better numbers, they will exceed 1.4 billion in cash flow improvement this year….
I’m optimistic Q4 will show even better numbers, they will exceed 1.4 billion in cash flow improvement this year….
I was encouraged by the 70% reduction in warranty claims. While some of that may be attributable to early release Air models coming off warranty, it is an encouraging sign of improvement as much of the service work is warranty related."Our significant investment in service has already cut wait times by around 20%, supported by a 40% increase in service technicians, 15% more mobile service capacity, and an expanded service footprint."
I don't think that can be said about any company let alone one with a -74 gross margin. At best the leadership is showing progress on their operational reset which builds some credibility. But they still burned through $1B in in the quarter and even with the $1.75B further commitment by the PIF only have enough cash to get through Q4 2027. They're accomplishing their short term objectives by producing and selling fewer cars. That's a survival story, not a growth one. It will take billions of additional investment and years before the company comes anywhere close to profitability. And there's no guarantee of that.Like I’ve always been saying…..they will never go bankrupt…..PIF will support until they establish. Napoli is looking to be the perfect choice for CEO.
I’m optimistic Q4 will show even better numbers, they will exceed 1.4 billion in cash flow improvement this year….

- Joined
- Nov 6, 2026
- Messages
- 3
- Reaction score
- 7
- Cars
- 2023 Lucid Air Pure AWD
I am still optimistic in the company's future. The earnings call didn't increase or decrease the belief.
What I want to see is:
-consistent, measured improvements and features introduced through their OTA schedule.
-the continued expansion of the service centers
-Cosmos and Earth to allow them to reach a larger market
While I am a new as an owner, I have held the stock for several years and continue to believe they will get solid footing.
What I want to see is:
-consistent, measured improvements and features introduced through their OTA schedule.
-the continued expansion of the service centers
-Cosmos and Earth to allow them to reach a larger market
While I am a new as an owner, I have held the stock for several years and continue to believe they will get solid footing.
- Joined
- May 19, 2025
- Messages
- 536
- Reaction score
- 699
- Cars
- BMW X1
a significant portion of their current burn is due to AMP2 and the midsize programI don't think that can be said about any company let alone one with a -74 gross margin. At best the leadership is showing progress on their operational reset which builds some credibility. But they still burned through $1B in in the quarter and even with the $1.75B further commitment by the PIF only have enough cash to get through Q4 2027. They're accomplishing their short term objectives by producing and selling fewer cars. That's a survival story, not a growth one. It will take billions of additional investment and years before the company comes anywhere close to profitability. And there's no guarantee of that.
Yes it is. But there will be other cap ex needs as the midsize program gets closer to launch. Namely the build out of the sales and service organization. There's going to need to be major investments to take the company from a niche manufacturer to one that can sell and service vehicles at volume. It might not be on the level of the investments made to bring Cosmos to market, but it won't be inconsequential.a significant portion of their current burn is due to AMP2 and the midsize program
Cosmos & Earth cannot meaningfully increase sales without a large investment in sales, service and inventory. All eat cash! I don't envy the Lucid team. Today I wrote my Q3 report to my shareholders and let me tell you when you have 68% product gross margin everything is easy!

- Joined
- Mar 27, 2025
- Messages
- 1,322
- Reaction score
- 1,791
- Cars
- GGT, BMW i3
They also missed pretty much every target and the 4% year over year growth was driven by heavy incentives on existing inventory. Plus the PIF money is a loan, not an investment.I don't think that can be said about any company let alone one with a -74 gross margin. At best the leadership is showing progress on their operational reset which builds some credibility. But they still burned through $1B in in the quarter and even with the $1.75B further commitment by the PIF only have enough cash to get through Q4 2027. They're accomplishing their short term objectives by producing and selling fewer cars. That's a survival story, not a growth one. It will take billions of additional investment and years before the company comes anywhere close to profitability. And there's no guarantee of that.
The only positive is the improved cash flow position from cost savings

And reduced warranty costsThey also missed pretty much every target and the 4% year over year growth was driven by heavy incentives on existing inventory. Plus the PIF money is a loan, not an investment.
The only positive is the improved cash flow position from cost savings
- Joined
- Jun 22, 2024
- Messages
- 1,595
- Reaction score
- 1,326
- Location
- Naperville, IL
- Cars
- 14 CR-V EXL, 26GravityGT
- Referral Code
- W772ZCOT
Yeah I feel like the initial 2025-2026 build Gravities have the hardware gremlins at least triaged and they know where they are after sitting in a SC being studied for 6 months....

- Joined
- Mar 7, 2025
- Messages
- 207
- Reaction score
- 272
- Location
- Westchester, NY
- Cars
- 25 AT, 23 Subaru Ascent
- Referral Code
- 8W0TRV52
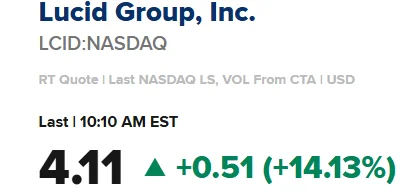
As of this morning, the market seems to have a positive take-away
- Joined
- Jan 3, 2022
- Messages
- 7,602
- Reaction score
- 8,735
- Location
- San Francisco Bay Area
- Cars
- Gravity GT, XC40 P8 EV
- Referral Code
- 3OKY7YGA
As of this morning, the market seems to have a positive take-away..
For a few hours, or a day.
